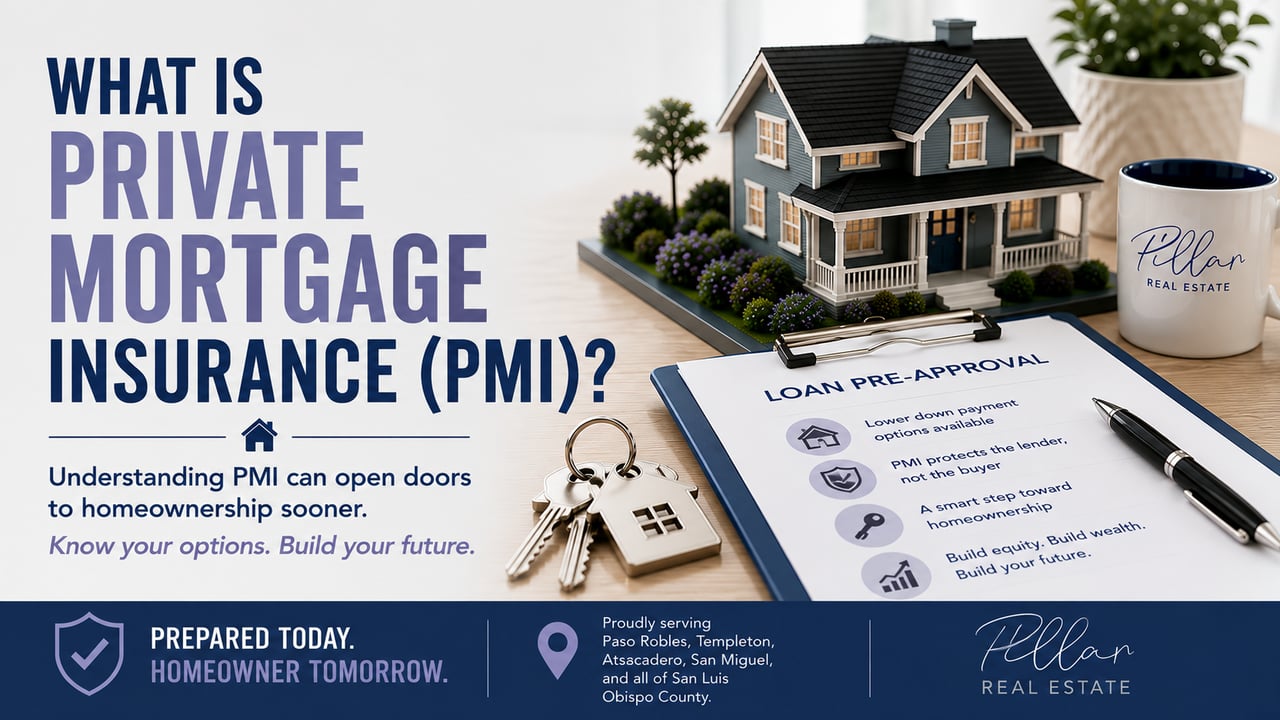
What Is Private Mortgage Insurance (PMI)?
August 20, 2026
August 20, 2026
One of the questions I hear from first-time buyers is,
"What is PMI, and do I have to pay it?"
If you've started talking with a lender or researching mortgage options, you've probably seen the term Private Mortgage Insurance, or PMI.
For some buyers, just hearing the word "insurance" makes it sound like another expensive fee.
But here's the thing.
PMI isn't necessarily something to avoid.
For many buyers, it's what makes buying a home possible without waiting years to save for a larger down payment.
If you're buying a home in Paso Robles, Templeton, Atascadero, San Miguel, or anywhere in San Luis Obispo County, understanding PMI will help you make more informed decisions about your financing options.
Over the past 13+ years, I've helped buyers with many different budgets and financing situations. One thing I've learned is that every buyer's path to homeownership looks a little different. My goal is to help you understand your options so you can choose the strategy that makes the most sense for your goals.
Before we get started, I also recommend reading my article, "What Is a Mortgage Pre-Approval and Why Should I Get One?" Getting pre-approved is often the first step in understanding what loan options, including PMI, may be available to you.
What Is Private Mortgage Insurance?
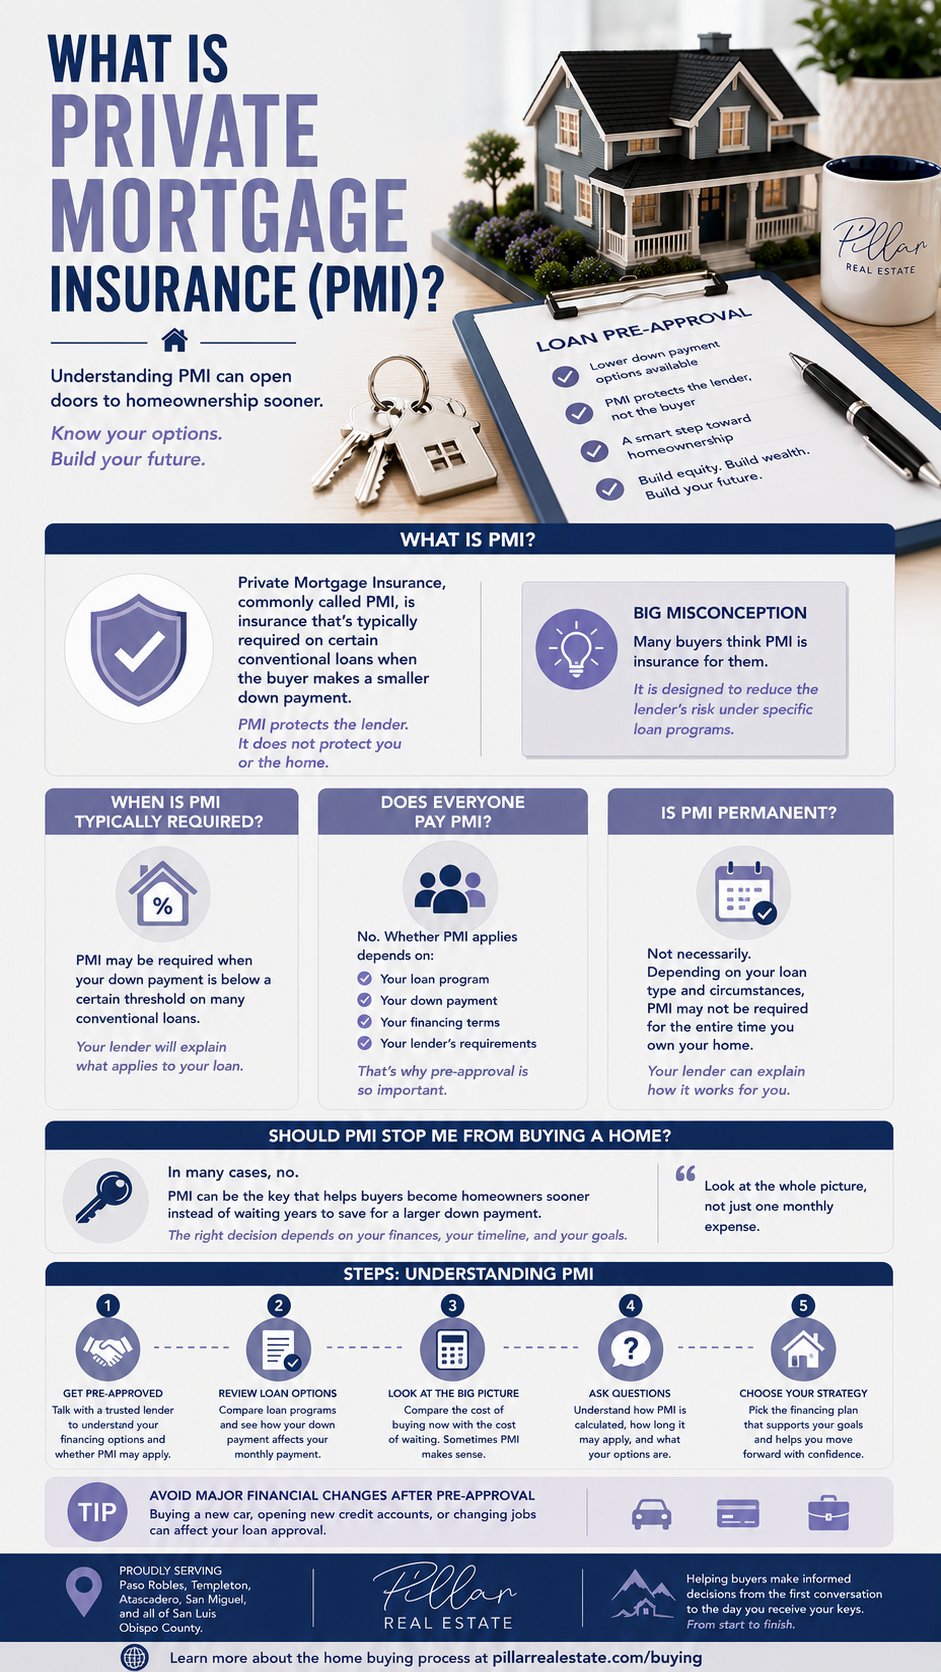
Private Mortgage Insurance, commonly called PMI, is insurance that's typically required on certain conventional loans when the buyer makes a smaller down payment.
PMI generally protects the lender.
It does not insure the buyer or protect the home itself.
This is one of the biggest misconceptions I hear.
Many buyers assume that because they're paying for PMI, it's protecting them.
Instead, it's designed to reduce the lender's risk under specific loan programs.
When Is PMI Typically Required?
Whether PMI is required depends on your loan program and your individual financing situation.
Many conventional loans require PMI when the down payment is below a certain threshold.
Your lender will explain whether PMI applies to your loan and how it's calculated.
Every buyer's situation is different, so it's important to review your financing options before making assumptions.
Does Everyone Pay PMI?
No.
Some buyers will have PMI.
Others won't.
It depends on factors such as:
That's one reason I always recommend talking with a lender early in the process.
Understanding your options helps you compare different loan scenarios instead of focusing on just one number.
Is PMI Permanent?
Not necessarily.
Depending on your loan type and circumstances, PMI may not be something you pay for the entire time you own your home.
Your lender can explain how PMI works for your specific loan, including when it may end and what requirements apply.
This is another reason I encourage buyers to ask questions early.
Understanding the long-term picture helps you make better decisions today.
Should PMI Stop Me From Buying a Home?
In my experience, the answer is often no.
I've seen buyers delay purchasing a home because they were trying to avoid PMI.
Sometimes that makes sense.
Sometimes it doesn't.
Every situation is different.
If waiting means missing out on years of building equity or delaying your goals, PMI may simply be part of the strategy that helps you become a homeowner sooner.
The right decision depends on your finances, your timeline, and what makes sense for your goals.
That's why I believe it's important to look at the whole picture instead of focusing on one monthly expense.
What I'm Seeing Right Now
One thing I've noticed is that buyers often hear negative things about PMI before they understand what it actually is.
Once we talk through how it works, the conversation changes.
Instead of asking, "How do I avoid PMI?" they start asking, "Which financing option makes the most sense for me?"
That's a much better question.
Buying a home isn't about finding the perfect loan.
It's about finding the right strategy for your situation.
When you understand your options, you can move forward with confidence.
From start to finish.
A Real-Life Example
I met with buyers who had already been talking with a lender.
Everything was going well until they received an estimate of their monthly payment.
One line caught their attention.
PMI.
They immediately asked,
"Is this a bad thing?"
I told them not to jump to conclusions.
Instead, let's look at the whole picture.
We talked about what PMI actually is, why it was part of their loan, and how it fit into their overall financial plan.
Then we compared two scenarios.
One was waiting longer to save a larger down payment.
The other was buying the home they wanted now and paying PMI for a period of time.
Once they saw both options side by side, the decision became much easier.
Instead of focusing on one line item, they focused on what helped them reach their long-term goals.
That's exactly how I believe buyers should approach decisions like this.
The Biggest Mistake
The biggest mistake I see is assuming PMI automatically means it's a bad loan.
It doesn't.
PMI is simply one piece of a financing strategy.
For many buyers, it's what allows them to purchase a home sooner instead of waiting years to save a larger down payment.
Another common mistake is trying to avoid PMI at all costs without considering how rising home prices, interest rates, or missed opportunities might affect the bigger financial picture.
That's why I always encourage buyers to look at the complete cost of waiting versus buying now.
What This Process Should Feel Like
When you review your financing options, I don't want you to focus on one fee.
I want you to understand the entire strategy.
By the time you choose your loan, you should know:
Why PMI may apply.
How it affects your monthly payment.
When it may no longer be required.
And whether buying now or waiting better fits your goals.
That's the kind of conversation that leads to confident decisions.
How This Connects to the Bigger Picture
In my previous article, "What Is a Mortgage Pre-Approval and Why Should I Get One?", I explained why talking with a lender early helps you understand your buying power before you begin your home search.
PMI is often one of the financing topics that comes up during that conversation.
The more you understand your loan options before you start shopping, the easier it becomes to focus on finding the right home instead of worrying about financing later.
Next, we'll answer another question buyers often ask when they're looking at different communities:
What Is an HOA and What Does It Cover?
Steps: Understanding Private Mortgage Insurance (PMI)
Step 1: Get Pre-Approved
If you're buying a home in Paso Robles, Templeton, Atascadero, San Miguel, or anywhere in San Luis Obispo County, start by talking with a trusted lender.
They'll explain your financing options and whether PMI may apply to your loan.
Step 2: Review Your Loan Options
Not every loan works the same way.
Compare different loan programs and ask how your down payment affects your monthly payment and whether PMI is required.
Step 3: Look at the Complete Financial Picture
Don't focus on just one monthly expense.
Compare the cost of buying now with the cost of waiting.
Sometimes paying PMI for a period of time makes more financial sense than delaying your purchase.
Step 4: Ask Questions
If you don't understand how PMI works, ask.
Your lender can explain how it's calculated, how long it may apply, and what options are available based on your loan program.
Step 5: Choose the Strategy That Fits Your Goals
The best loan isn't always the one with the lowest payment.
It's the one that supports your long-term financial goals and helps you move forward with confidence.
So... What Is Private Mortgage Insurance?
Private Mortgage Insurance, or PMI, is insurance that's required with some conventional loans when buyers make a smaller down payment.
It generally protects the lender, not the buyer.
For many people, PMI isn't an obstacle.
It's simply one tool that makes homeownership possible sooner.
The Best Financial Decisions Look Beyond One Monthly Payment
Over the past 13+ years, I've learned that buyers make the best decisions when they understand all of their options.
PMI shouldn't automatically scare you away from buying a home.
Instead, it should become one part of a larger conversation about your goals, your budget, and your timeline.
When you understand the complete picture, you can choose the financing strategy that makes the most sense for you.
From start to finish.
The Real Question to Ask
Instead of asking:
"How do I avoid PMI?"
Ask:
"Does paying PMI help me become a homeowner sooner, and does that make sense for my financial goals?"
That's the question that helps you make a thoughtful decision instead of reacting to a single line item on your loan estimate.
Next Steps
If you're planning to buy a home in Paso Robles, Templeton, Atascadero, San Miguel, or anywhere in San Luis Obispo County, I recommend starting with a conversation about your financing options.
I also encourage you to read my article, "What Is a Mortgage Pre-Approval and Why Should I Get One?" because understanding your financing before you start shopping is one of the best ways to reduce stress and make confident decisions.
When you're ready to begin your home search, I'd love to help.
👉 https://pillarrealestate.com/buying
My goal is to help you understand every step of the process, answer your questions honestly, and help you make decisions that fit your goals.
From start to finish.
FAQ
What is Private Mortgage Insurance (PMI)?
Private Mortgage Insurance, or PMI, is insurance that's typically required on certain conventional loans when a buyer makes a smaller down payment. It generally protects the lender rather than the buyer.
Does everyone have to pay PMI?
No. Whether PMI applies depends on your loan program, down payment, financing terms, and lender requirements.
Does PMI protect me as the buyer?
Generally, no. PMI is designed to protect the lender under certain loan programs. Your lender can explain how it applies to your specific loan.
Is PMI permanent?
Not necessarily. Depending on your loan and circumstances, PMI may end after certain requirements are met. Your lender can explain how that works for your loan.
Should PMI keep me from buying a home?
Not always. For many buyers, PMI is simply part of a financing strategy that allows them to purchase a home sooner rather than waiting to save a larger down payment.
Who can help me understand whether PMI applies to my loan?
Your lender can explain whether PMI is required, how it's calculated, and what financing options are available based on your individual situation.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
[email protected]
1345 Park St. Paso Robles, CA 93446
DRE# 01925434
Amber Johnson | September 12, 2026

Amber Johnson | September 11, 2026

Amber Johnson | September 11, 2026

Amber Johnson | September 11, 2026
Amber Johnson | September 10, 2026
Amber Johnson | September 9, 2026
Amber Johnson | September 9, 2026
Amber Johnson | September 9, 2026
Amber Johnson | September 9, 2026
You’ve got questions and we can’t wait to answer them.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
DRE# 01925434
1345 Park Street
Paso Robles, CA 93446