What To Save for When Buying a Home
January 13, 2025
January 13, 2025
Knowing what to budget for when buying a home may feel intimidating — but it doesn’t have to be. By understanding the costs you may encounter upfront, you can take control of the process.
Here are just a few things experts say you should be thinking about as you plan ahead.
Saving for your down payment is likely top of mind. But how much do you really need? A common misconception is that you have to put down 20% of the purchase price. But that’s not necessarily the case. Unless it’s specified by your loan type or lender, you don’t have to. There are some home loan options that require as little as 3.5% or even 0% down. An article from The Mortgage Reports explains:
“The amount you need to put down will depend on a variety of factors, including the loan type and your financial goals. If you don’t have a large down payment saved up, don’t worry—there are plenty of options available . . .”
A trusted lender will go over the various loan types with you, any down payment requirements on those, and down payment assistance programs you may qualify for. The more you know ahead of time, the easier the process will be. And the key to getting the information you need is working with a pro to see what’ll work best for your situation.
Make sure you also budget for closing costs, which are a collection of fees and payments made to the various parties involved in your transaction. Bankrate explains:
“Mortgage closing costs are the fees associated with buying a home that you must pay on closing day. Closing costs typically range from 2 to 5 percent of the total loan amount, and they include fees for the appraisal, title insurance and origination and underwriting of the loan.”
When it comes to closing costs, a trusted lender can guide you through specifics and answer any questions you may have. They can also give you a better idea of how much you should be prepared to pay so you can cruise through your closing with confidence.
And as you plan ahead for closing day, be sure to budget for your real estate agent’s professional service fee too, in case the seller doesn’t cover it. But don’t worry, you’ll work with your agent ahead of time to agree on what this is, so you won’t be surprised at the finish line.
And if you want to cover all your bases, you can also consider saving for an earnest money deposit (EMD). According to Realtor.com, an EMD is typically between 1% and 2% of the total home price and is money you pay as a show of good faith when you make an offer on a house.
But, it’s not an added expense. Instead, it works like a credit and goes toward some of your upfront costs. You’re simply using some of the money you’ve already saved for your purchase to show the seller you’re committed and serious about buying their house. Realtor.com describes how it works as part of your sale:
“It tells the real estate seller you’re in earnest as a buyer . . . Assuming that all goes well and the buyer’s good-faith offer is accepted by the seller, the earnest money funds go toward the down payment and closing costs. In effect, earnest money is just paying more of the down payment and closing costs upfront.”
Keep in mind, this isn’t required, and it doesn’t guarantee your offer will be accepted. It’s important to work with a real estate advisor to understand what’s best for your situation and any specific requirements in your local area. They’ll advise you on what moves you should make so you can make the best possible decisions throughout the buying process.
The key to a successful homebuying savings strategy? Being informed about what you need to save for. Because, when you understand what to expect, you can plan ahead. With an expert agent and a trusted lender, you’ll have the information you need to move forward with confidence.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
[email protected]
1345 Park St. Paso Robles, CA 93446
DRE# 01925434
Amber Johnson | October 21, 2026
Amber Johnson | October 21, 2026
Amber Johnson | October 21, 2026
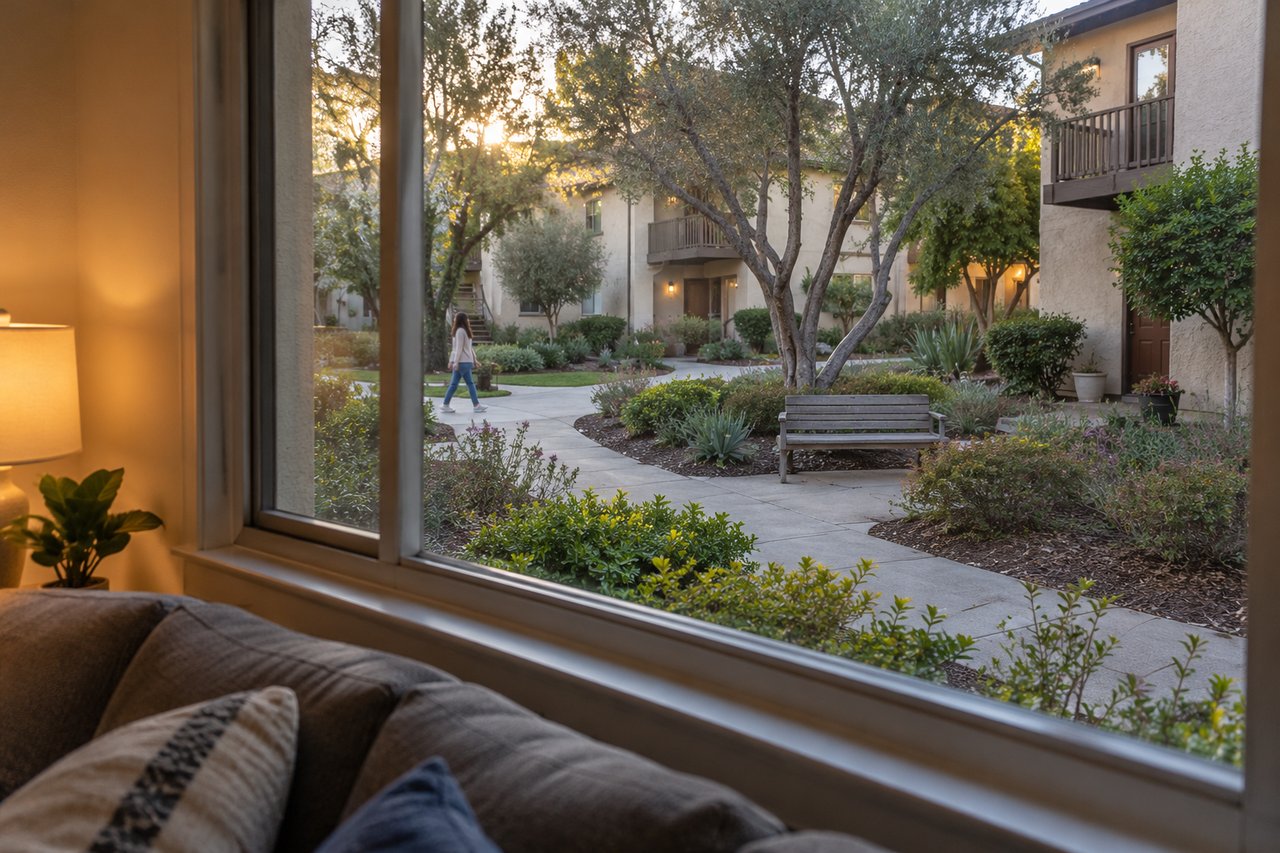
Check privacy, shared-space rules and activity near the unit before deciding whether courtyard-facing condo living suits you.
Amber Johnson | October 20, 2026
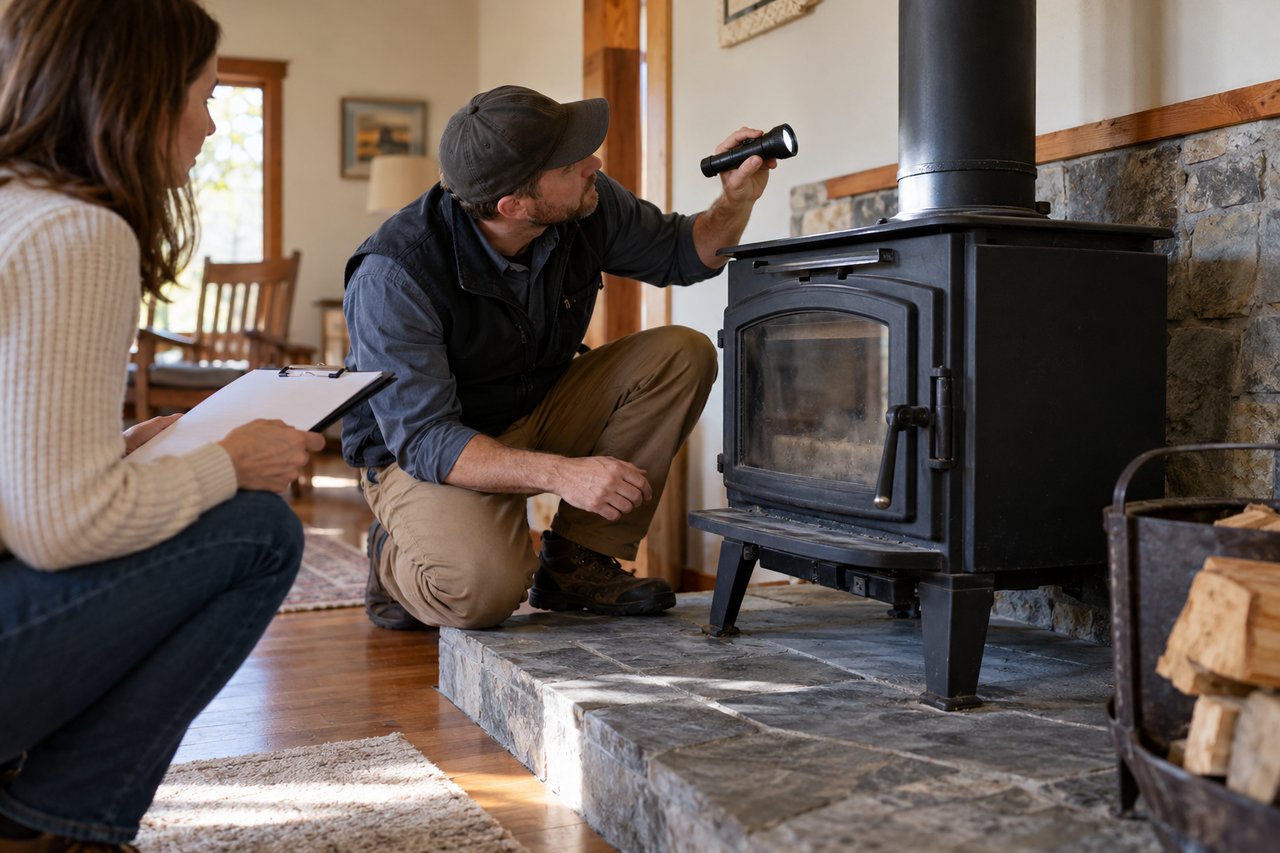
Review the stove, venting, documentation and insurance questions before treating wood heat as a benefit of the purchase.
Amber Johnson | October 20, 2026
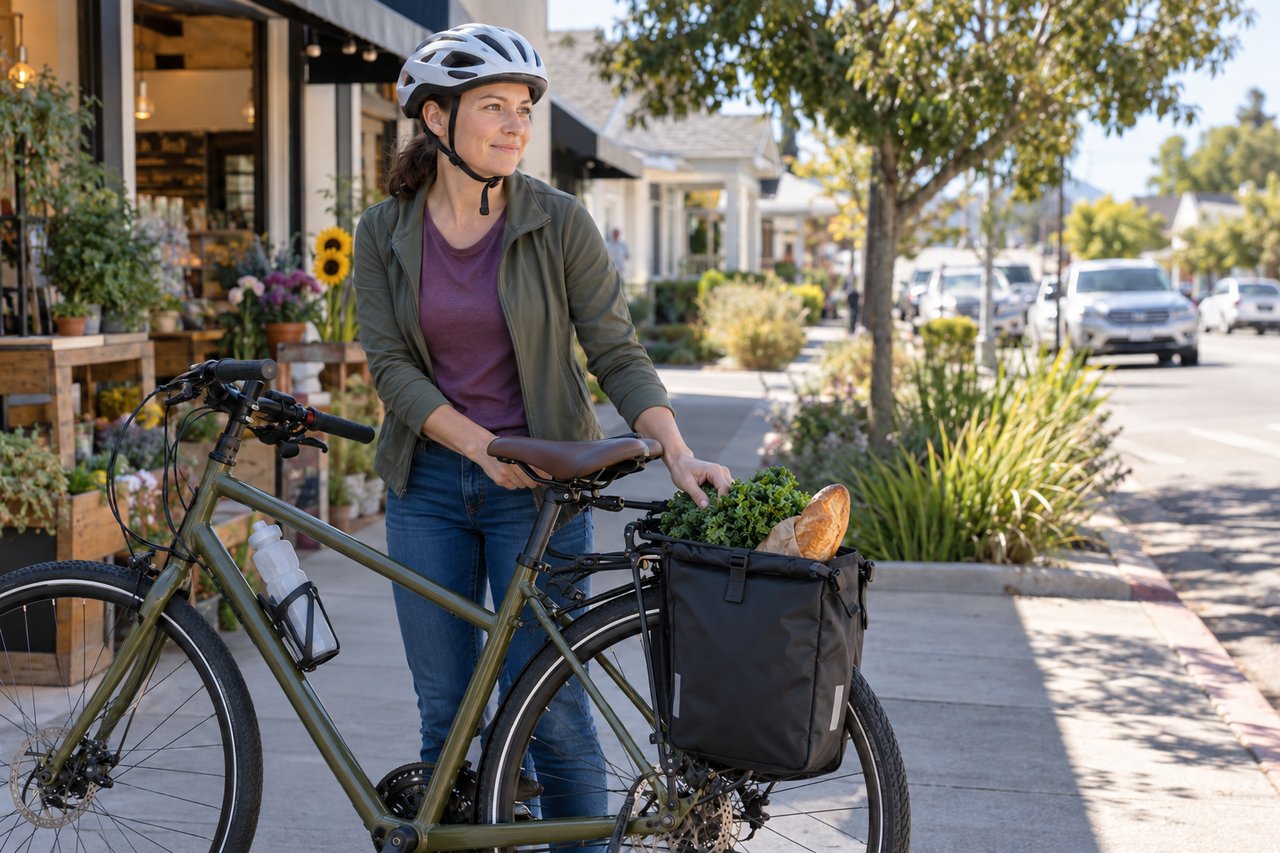
Test the routes to your actual errands, what you need to carry and your backup options before choosing a home around cycling.
Amber Johnson | October 20, 2026
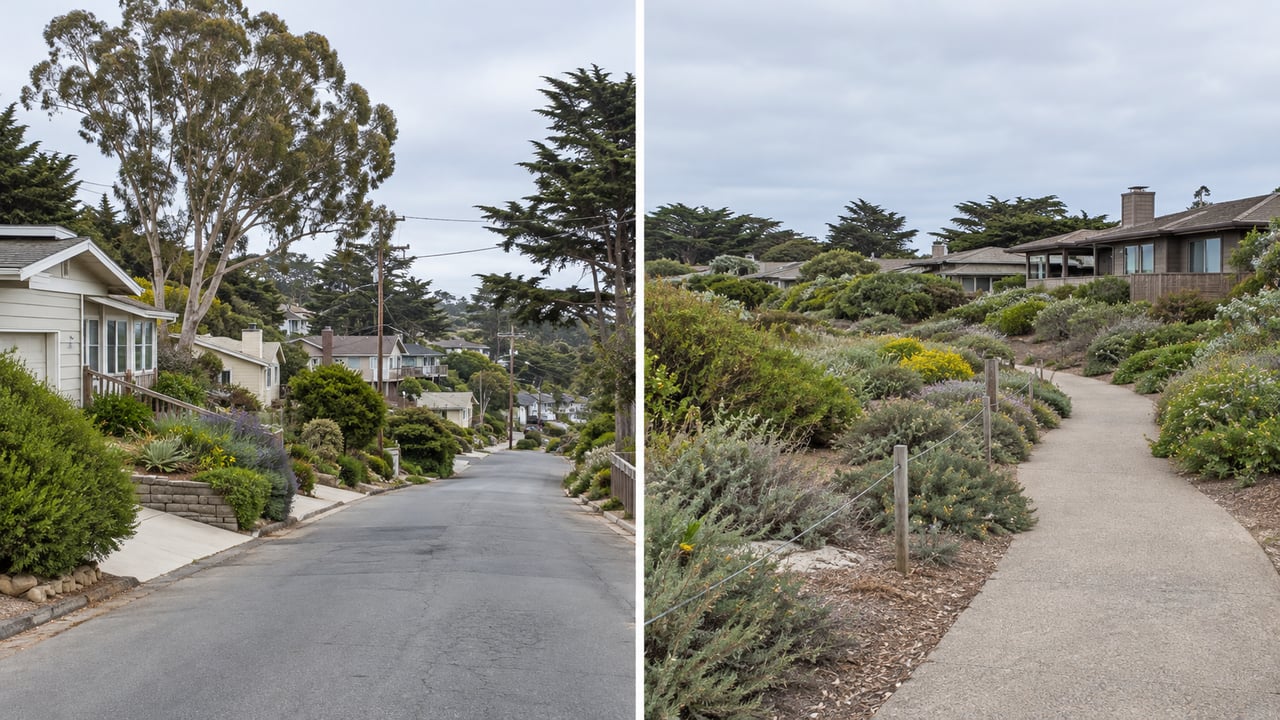
Compare these two Morro Bay areas through the specific homes, daily routes and property features that matter to your household.
Amber Johnson | October 20, 2026
Check the property’s jurisdiction, current home-business rules and private restrictions before assuming clients can visit your home.
Amber Johnson | October 20, 2026
Compare keeping the pool with removal, site restoration and buyer appeal before spending money on pre-sale work.
Amber Johnson | October 20, 2026
Compare a consistent property type and reporting period within relevant price brackets before treating a broad market headline as guidance for a particular home.
You’ve got questions and we can’t wait to answer them.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
DRE# 01925434
1345 Park Street
Paso Robles, CA 93446