Why Today’s Housing Market Isn’t Headed for a Crash
February 9, 2023
February 9, 2023
67% of Americans say a housing market crash is imminent in the next three years. With all the talk in the media lately about shifts in the housing market, it makes sense why so many people feel this way. But there’s good news. Current data shows today’s market is nothing like it was before the housing crash in 2008.
During the lead-up to the housing crisis, it was much easier to get a home loan than it is today. Banks were creating artificial demand by lowering lending standards and making it easy for just about anyone to qualify for a home loan or refinance an existing one.
As a result, lending institutions took on much greater risk in both the person and the mortgage products offered. That led to mass defaults, foreclosures, and falling prices. Today, things are different, and purchasers face much higher standards from mortgage companies.
The graph below uses data from the Mortgage Bankers Association (MBA) to help tell this story. In this index, the higher the number, the easier it is to get a mortgage. The lower the number, the harder it is.
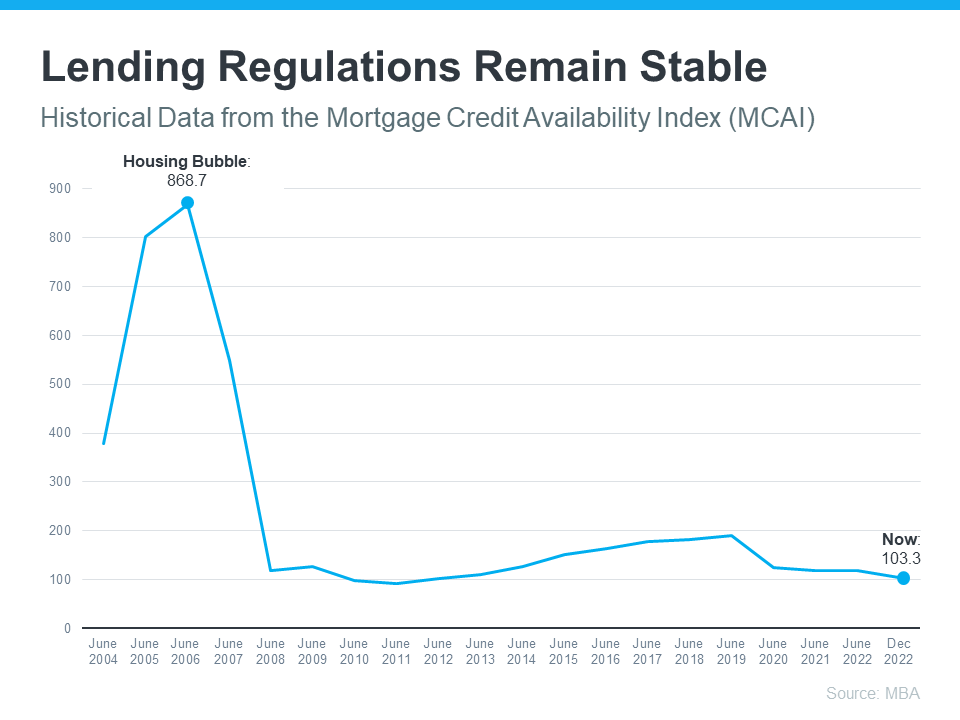
This graph also shows just how different things are today compared to the spike in credit availability leading up to the crash. Tighter lending standards have helped prevent a situation that could lead to a wave of foreclosures like the last time.
Another difference is the number of homeowners that were facing foreclosure when the housing bubble burst. Foreclosure activity has been lower since the crash, largely because buyers today are more qualified and less likely to default on their loans. The graph below uses data from ATTOM to show the difference between last time and now:
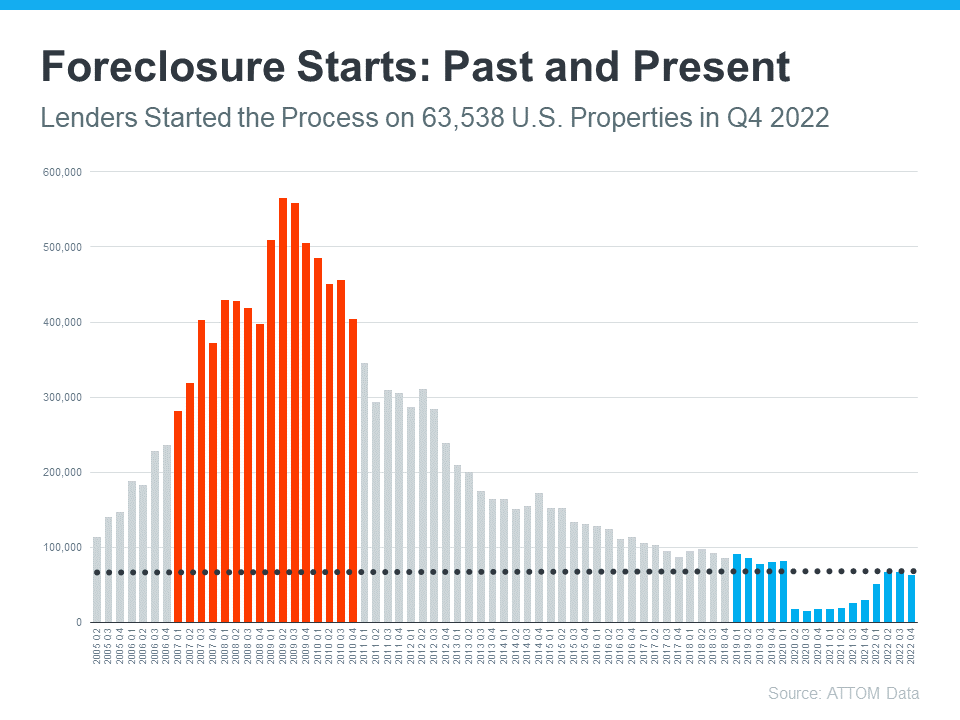
So even as foreclosures tick up, the total number is still very low. And on top of that, most experts don’t expect foreclosures to go up drastically like they did following the crash in 2008. Bill McBride, Founder of Calculated Risk, explains the impact a large increase in foreclosures had on home prices back then – and how that’s unlikely this time.
“The bottom line is there will be an increase in foreclosures over the next year (from record level lows), but there will not be a huge wave of distressed sales as happened following the housing bubble. The distressed sales during the housing bust led to cascading price declines, and that will not happen this time.”
For historical context, there were too many homes for sale during the housing crisis (many of which were short sales and foreclosures), and that caused prices to fall dramatically. Supply has increased since the start of this year, but there’s still a shortage of inventory available overall, primarily due to years of underbuilding homes.
The graph below uses data from the National Association of Realtors (NAR) to show how the months’ supply of homes available now compares to the crash. Today, unsold inventory sits at just 2.7-months’ supply at the current sales pace, which is significantly lower than the last time. There just isn’t enough inventory on the market for home prices to come crashing down like they did last time, even though some overheated markets may experience slight declines.
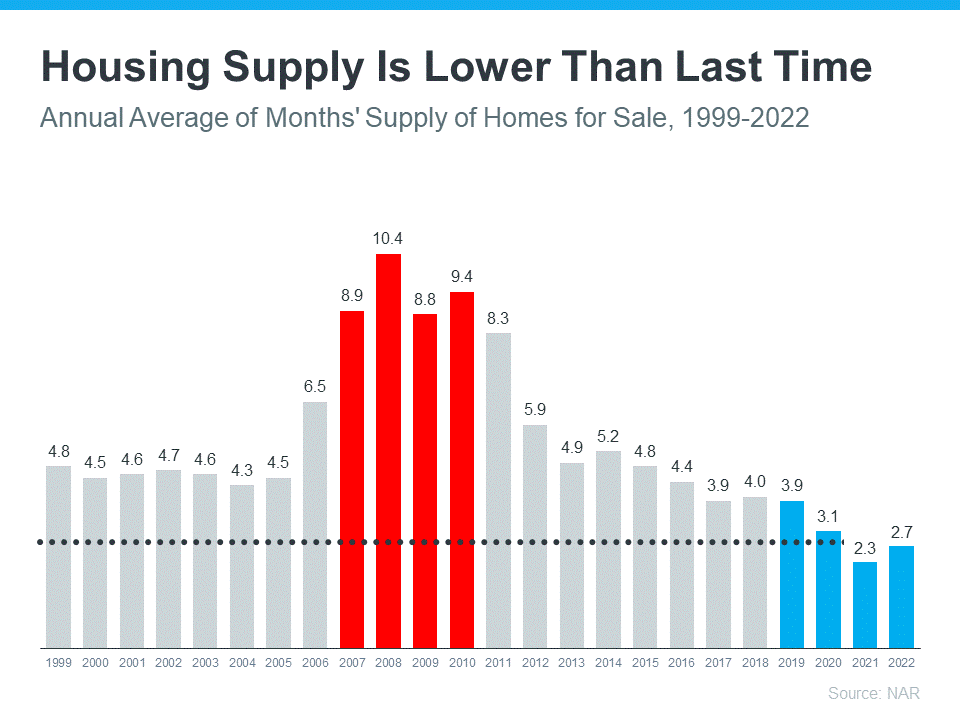
If recent headlines have you worried we’re headed for another housing crash, the data above should help ease those fears. Expert insights and the most current data clearly show that today’s market is nothing like it was last time.
Amber Johnson | October 24, 2026
Amber Johnson | October 21, 2026
Amber Johnson | October 21, 2026
Amber Johnson | October 21, 2026
Check privacy, shared-space rules and activity near the unit before deciding whether courtyard-facing condo living suits you.
Amber Johnson | October 20, 2026
Review the stove, venting, documentation and insurance questions before treating wood heat as a benefit of the purchase.
Amber Johnson | October 20, 2026
Test the routes to your actual errands, what you need to carry and your backup options before choosing a home around cycling.
Amber Johnson | October 20, 2026
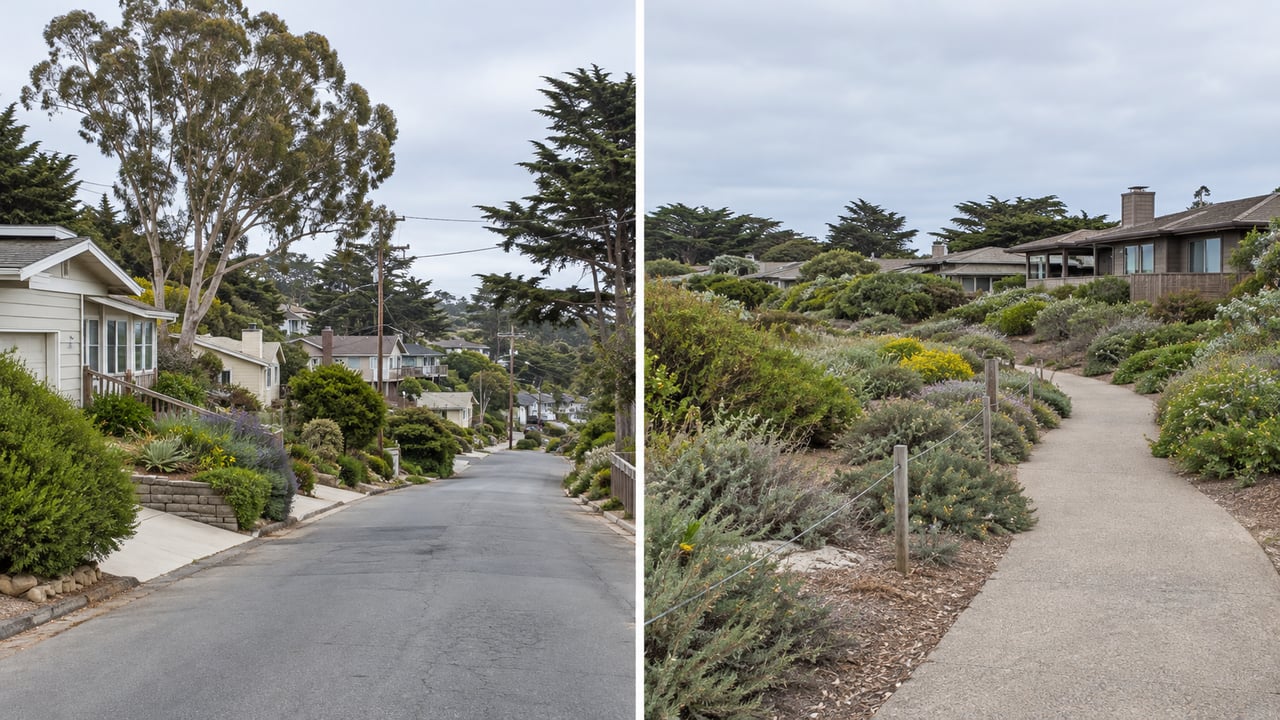
Compare these two Morro Bay areas through the specific homes, daily routes and property features that matter to your household.
Amber Johnson | October 20, 2026
Check the property’s jurisdiction, current home-business rules and private restrictions before assuming clients can visit your home.
Amber Johnson | October 20, 2026
Compare keeping the pool with removal, site restoration and buyer appeal before spending money on pre-sale work.
You’ve got questions and we can’t wait to answer them.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
DRE# 01925434
1345 Park Street
Paso Robles, CA 93446