Why a Foreclosure Wave Isn’t on the Horizon
July 23, 2024
July 23, 2024
Even though data shows inflation is cooling, a lot of people are still feeling the pinch on their wallets. And those high costs on everything from gas to groceries are fueling unnecessary concerns that more people are going to have trouble making their mortgage payments. But, does that mean there’s a big wave of foreclosures coming?
Here’s a look at why the data and the experts say that’s not going to happen.
One of the main reasons there were so many foreclosures during the last housing crash was because relaxed lending standards made it easy for people to take out mortgages, even when they couldn’t show they’d be able to pay them back. At that time, lenders weren’t being as strict when looking at applicant credit scores, income levels, employment status, and debt-to-income ratio.
But since then, lending standards have gotten a whole lot tighter. Lenders became much more diligent when assessing applicants for home loans. And that means we’re seeing more qualified buyers who have less of a risk of defaulting on their loans.
That’s why data from Freddie Mac and Fannie Mae shows the number of homeowners who are seriously behind on their mortgage payments (known in the industry as delinquencies) has been declining for quite some time. Take a look at the graph below: 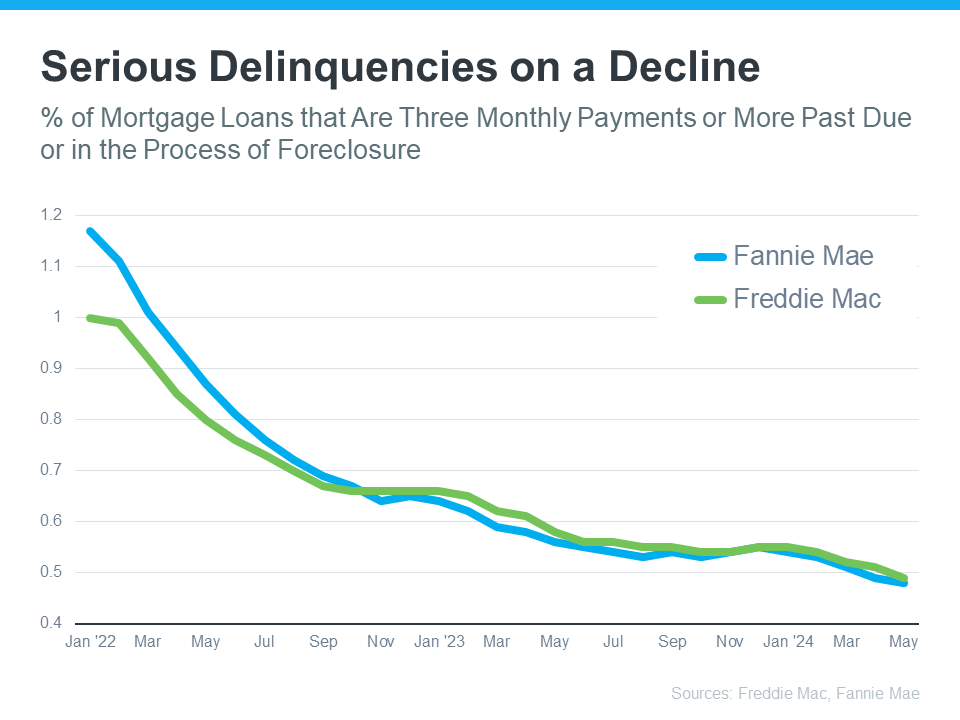
What this means is that, not only are borrowers more qualified, but they’re also finding ways to navigate through their challenges, exploring their repayment options, or maybe even using the record amount of equity they have to sell and avoid foreclosure entirely.
Before there can be a significant rise in foreclosures, the number of people who can’t make their mortgage payments would need to rise significantly. But, since so many buyers are making their payments today and homeowners have so much equity built up, a wave of foreclosures isn’t likely.
Take it from Bill McBride of Calculated Risk – an expert on the housing market who, after closely following the data and market leading up to the crash, was able to see the foreclosure crisis coming in 2008. McBride says:
“We will NOT see a surge in foreclosures that would significantly impact house prices (as happened following the housing bubble) for two key reasons: 1) mortgage lending has been solid, and 2) most homeowners have substantial equity in their homes.”
If you’re worried about a potential foreclosure crisis, know there’s nothing in the data to suggest that’ll happen. Buyers are more qualified now, and that’s one reason why they’re not falling seriously behind on their mortgage payments.
Amber Johnson | October 21, 2026
Amber Johnson | October 21, 2026
Amber Johnson | October 21, 2026
Check privacy, shared-space rules and activity near the unit before deciding whether courtyard-facing condo living suits you.
Amber Johnson | October 20, 2026
Review the stove, venting, documentation and insurance questions before treating wood heat as a benefit of the purchase.
Amber Johnson | October 20, 2026
Test the routes to your actual errands, what you need to carry and your backup options before choosing a home around cycling.
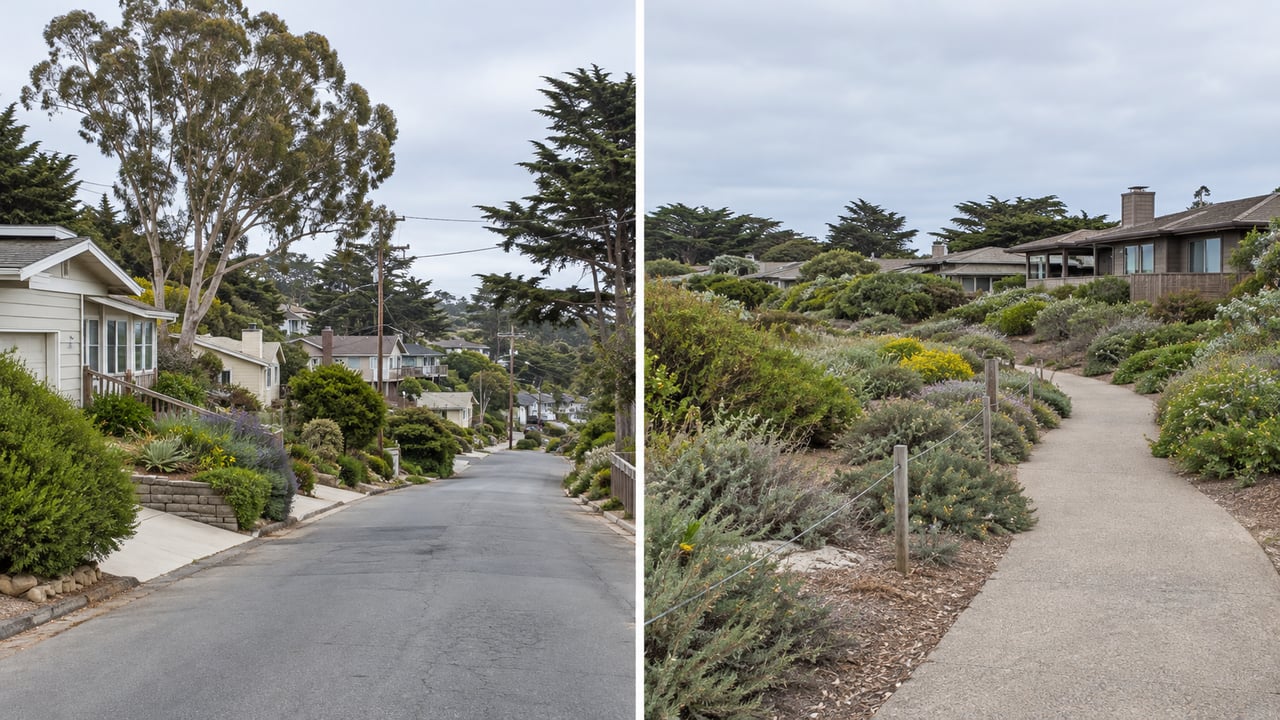
Amber Johnson | October 20, 2026
Compare these two Morro Bay areas through the specific homes, daily routes and property features that matter to your household.
Amber Johnson | October 20, 2026
Check the property’s jurisdiction, current home-business rules and private restrictions before assuming clients can visit your home.
Amber Johnson | October 20, 2026
Compare keeping the pool with removal, site restoration and buyer appeal before spending money on pre-sale work.
Amber Johnson | October 20, 2026
Compare a consistent property type and reporting period within relevant price brackets before treating a broad market headline as guidance for a particular home.
You’ve got questions and we can’t wait to answer them.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
DRE# 01925434
1345 Park Street
Paso Robles, CA 93446