The Main Reason Mortgage Rates Are So High
June 7, 2023

June 7, 2023
Today’s mortgage rates are top-of-mind for many homebuyers right now. As a result, if you’re thinking about buying for the first time or selling your current house to move into a home that better fits your needs, you may be asking yourself these two questions:
Here’s context you need to help answer those questions.
The 30-year fixed-rate mortgage is largely influenced by the supply and demand for mortgage-backed securities (MBS). According to Investopedia:
“Mortgage-backed securities (MBS) are investment products similar to bonds. Each MBS consists of a bundle of home loans and other real estate debt bought from the banks that issued them . . . The investor who buys a mortgage-backed security is essentially lending money to home buyers.”
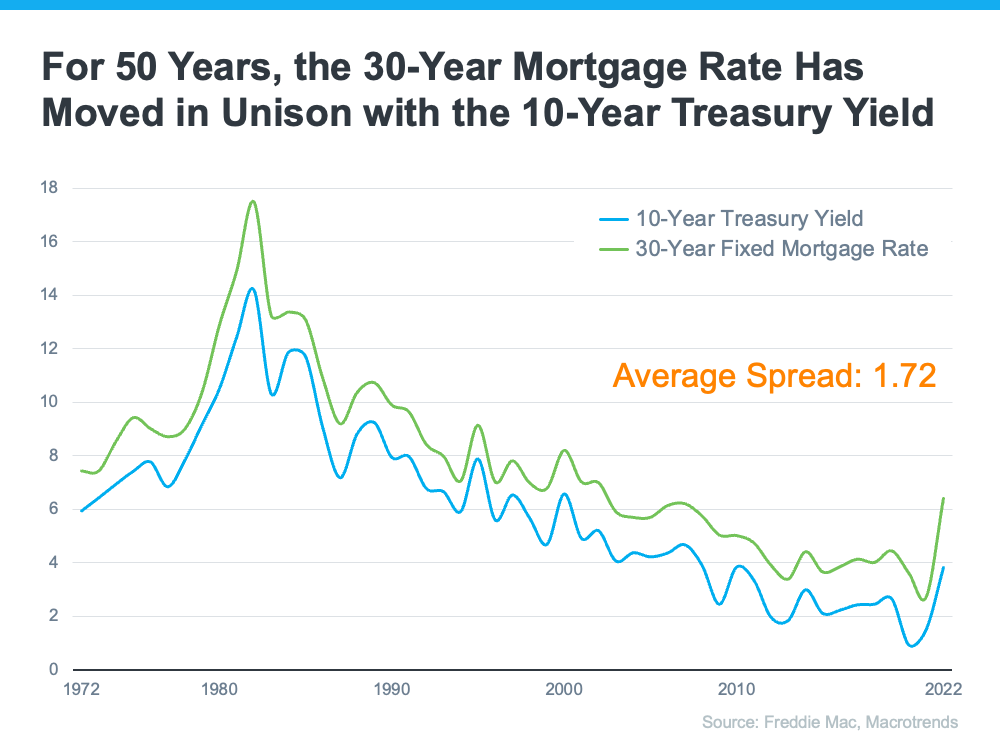
Demand for MBS helps determine the spread between the 10-Year Treasury Yield and the 30-year fixed mortgage rate. Historically, the average spread between the two is 1.72 (see chart below):
Last Friday morning, the mortgage rate was 6.85%. That means the spread was 3.2%, which is almost 1.5% over the norm. If the spread was at its historical average, mortgage rates would be 5.37% (3.65% 10-Year Treasury Yield + 1.72 spread).
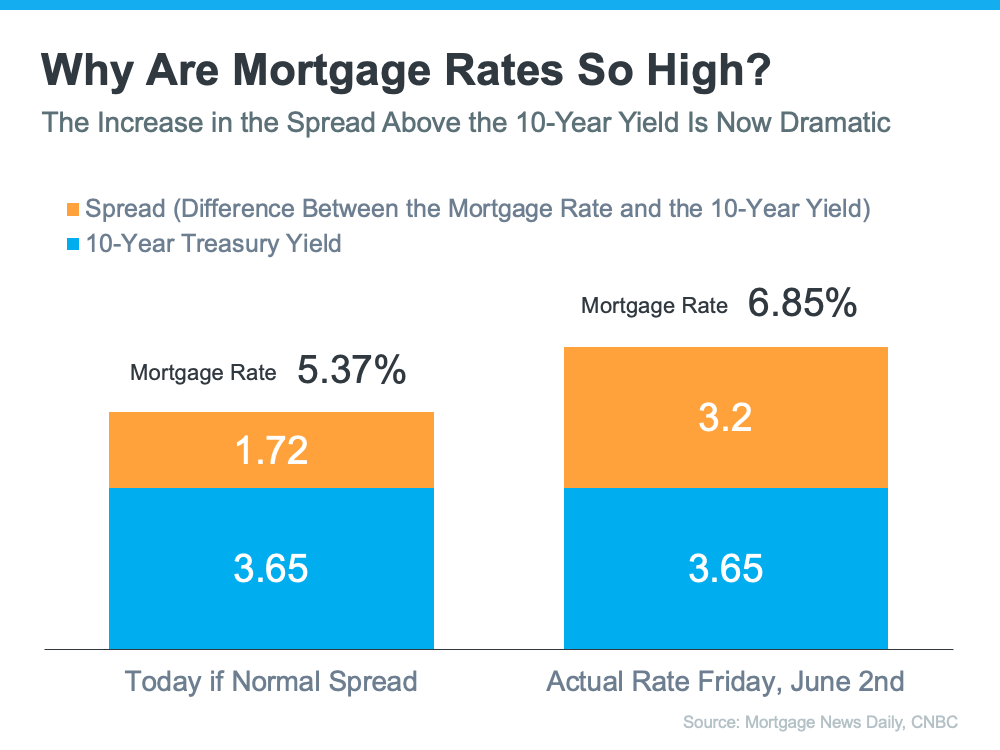
This large spread is very unusual. As George Ratiu, Chief Economist at Keeping Current Matters (KCM), explains:
“The only times the spread approached or exceeded 300 basis points were during periods of high inflation or economic volatility, like those seen in the early 1980s or the Great Financial Crisis of 2008-09."
The graph below uses historical data to help illustrate this point by showing the few times the spread has increased to 300 basis points or more:
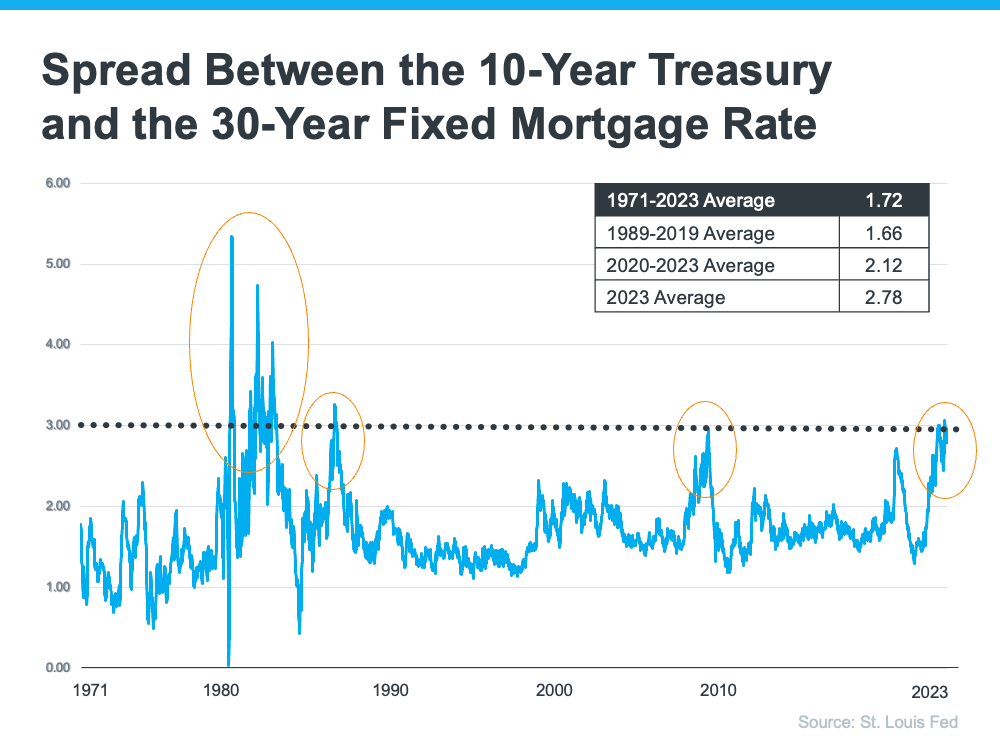
The graph shows how the spread has come down after each peak. The good news is, that means there’s room for mortgage rates to improve today.
So, what’s causing the larger spread and making mortgage rates so high today?
The demand for MBS is heavily influenced by the risks associated with investing in them. Today, that risk is impacted by broader market conditions like inflation and fear of a potential recession, the Fed’s interest rate hikes to try to bring down inflation, headlines that create unnecessarily negative narratives about home prices, and more.
Simply put: when there’s less risk, demand for MBS is high, so mortgage rates will be lower. On the other hand, if there’s more risk with MBS, demand for MBS will be low, and we’ll see higher mortgage rates as a result. Currently, demand for MBS is low, so mortgage rates are high.
Odeta Kushi, Deputy Chief Economist at First American, answers that question in a recent blog:
“It’s reasonable to assume that the spread and, therefore, mortgage rates will retreat in the second half of the year if the Fed takes its foot off the monetary tightening pedal and provides investors with more certainty. However, it’s unlikely that the spread will return to its historical average of 170 basis points, as some risks are here to stay.”
The spread will shrink when the fear investors feel is eased. That’ll mean we should see mortgage rates moderate as the year goes on. However, when it comes to forecasting mortgage rates, no one can know for sure exactly what will happen.
Amber Johnson | November 10, 2026
Learn what each listing outcome may mean, what it leaves unanswered and how price range, location and timing affect the comparison.
Amber Johnson | November 9, 2026
Amber Johnson | November 9, 2026
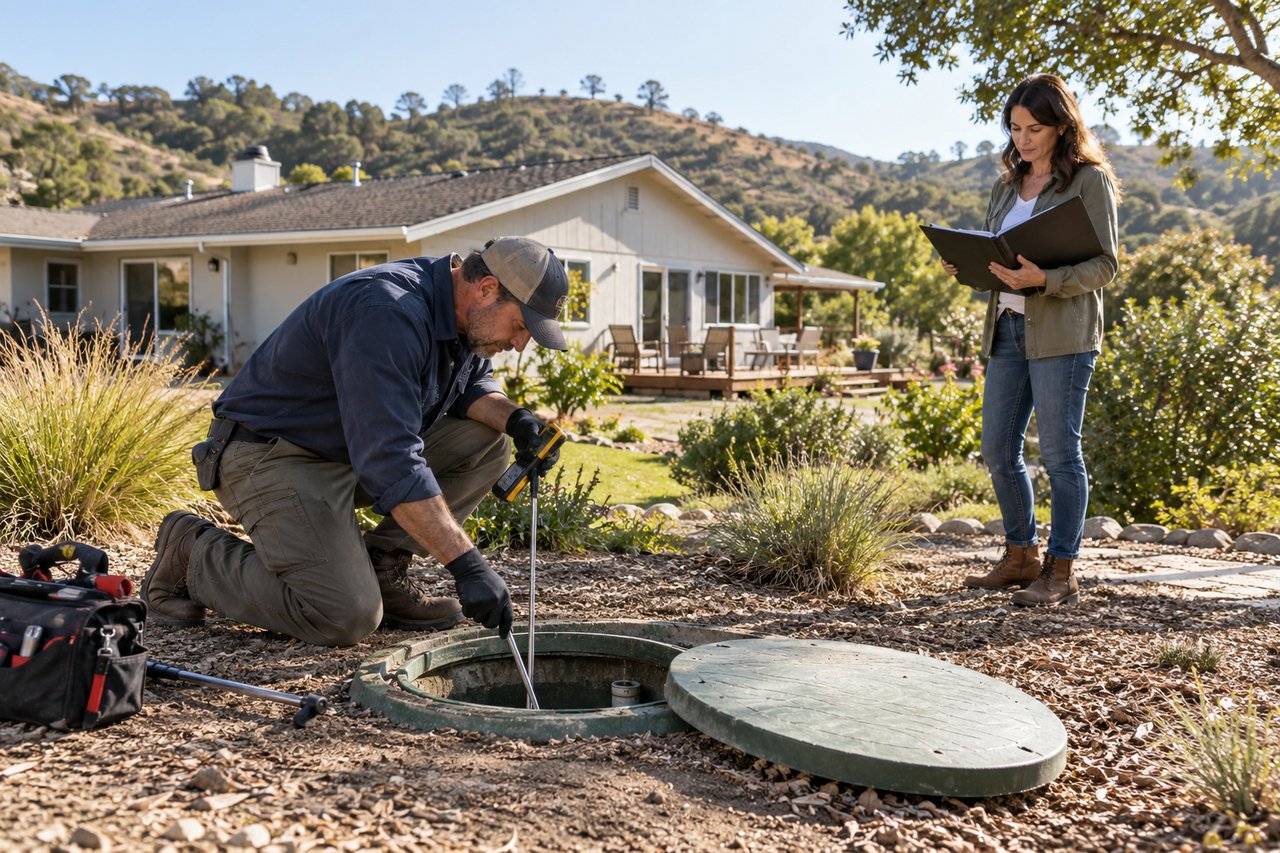
Review inspection findings, service records, capacity, access and local requirements before relying on the system.
Amber Johnson | November 8, 2026
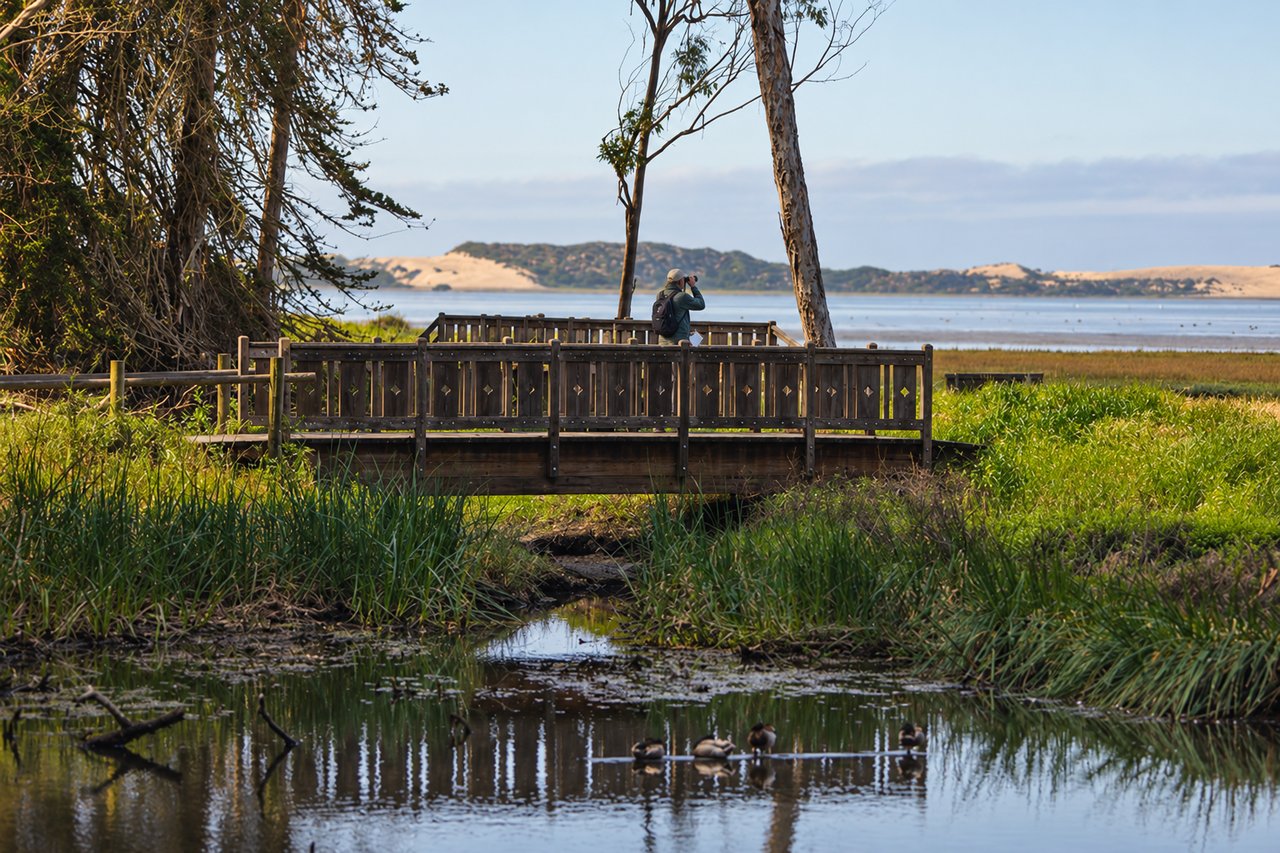
Compare access, timing, seasonal conditions and home-to-trail logistics before building regular birdwatching into life in Los Osos.
Amber Johnson | November 8, 2026
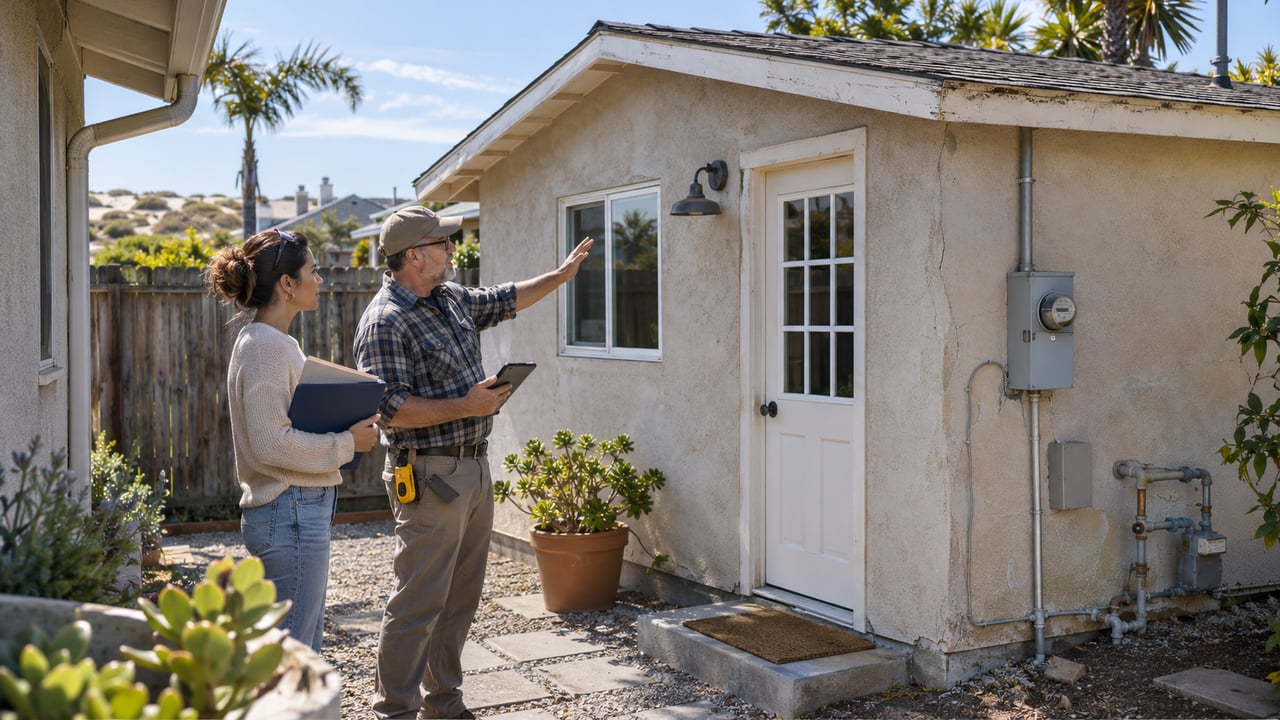
Verify the separate structure's records, condition and permitted use before counting on it.
Amber Johnson | November 7, 2026
Compare specific homes by their street setting, daily routes and access to the places you use.
Amber Johnson | November 7, 2026
Test school logistics, activities and daily routes from the specific home you are considering.
Amber Johnson | November 7, 2026
Amber Johnson | November 7, 2026
Show usable storage honestly and help buyers see how the home's layout fits daily life.
You’ve got questions and we can’t wait to answer them.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
DRE# 01925434
1345 Park Street
Paso Robles, CA 93446
