Lending Standards Are Not Like They Were Leading Up to the Crash
June 28, 2023

June 28, 2023
You might be worried we’re heading for a housing crash, but there are many reasons why this housing market isn’t like the one we saw in 2008. One of which is how lending standards are different today. Here’s a look at the data to help prove it.
Every month, the Mortgage Bankers Association (MBA) releases the Mortgage Credit Availability Index (MCAI). According to their website:
“The MCAI provides the only standardized quantitative index that is solely focused on mortgage credit. The MCAI is . . . a summary measure which indicates the availability of mortgage credit at a point in time.”
Basically, the index determines how easy it is to get a mortgage. Take a look at the graph below of the MCAI since they started keeping track of this data in 2004. It shows how lending standards have changed over time. It works like this:

In 2004, the index was around 400. But, by 2006, it had gone up to over 850. Today, the story is quite different. Since the crash, the index went down because lending standards got tighter, so today it’s harder to get a mortgage.
One of the main factors that contributed to the housing bubble was that lending standards were a lot less strict back then. Realtor.com explains it like this:
“In the early 2000s, it wasn’t exactly hard to snag a home mortgage. . . . plenty of mortgages were doled out to people who lied about their incomes and employment, and couldn’t actually afford homeownership.”
The tall peak in the graph above indicates that leading up to the housing crisis, it was much easier to get credit, and the requirements for getting a loan were far from strict. Back then, credit was widely available, and the threshold for qualifying for a loan was low.
Lenders were approving loans without always going through a verification process to confirm if the borrower would likely be able to repay the loan. That means creditors were lending to more borrowers who had a higher risk of defaulting on their loans.
As mentioned, lending standards have changed a lot since then. Bankrate describes the difference:
“Today, lenders impose tough standards on borrowers – and those who are getting a mortgage overwhelmingly have excellent credit.”
If you look back at the graph, you’ll notice after the peak around the time of the housing crash, the line representing the index went down dramatically and has stayed low since. In fact, the line is far below where standards were even in 2004 – and it’s getting lower. Joel Kan, VP and Deputy Chief Economist at MBA, provides the most recent update from May:
“Mortgage credit availability decreased for the third consecutive month . . . With the decline in availability, the MCAI is now at its lowest level since January 2013.”
The decreasing index suggests standards are getting much tougher – which makes it clear we’re far away from the extreme lending practices that contributed to the crash.
Leading up to the housing crash, lending standards were much more relaxed with little evaluation done to measure a borrower’s potential to repay their loan. Today, standards are tighter, and the risk is reduced for both lenders and borrowers. This goes to show, these are two very different housing markets, and this market isn’t like the last time.
Amber Johnson | November 10, 2026
Learn what each listing outcome may mean, what it leaves unanswered and how price range, location and timing affect the comparison.
Amber Johnson | November 9, 2026
Amber Johnson | November 9, 2026
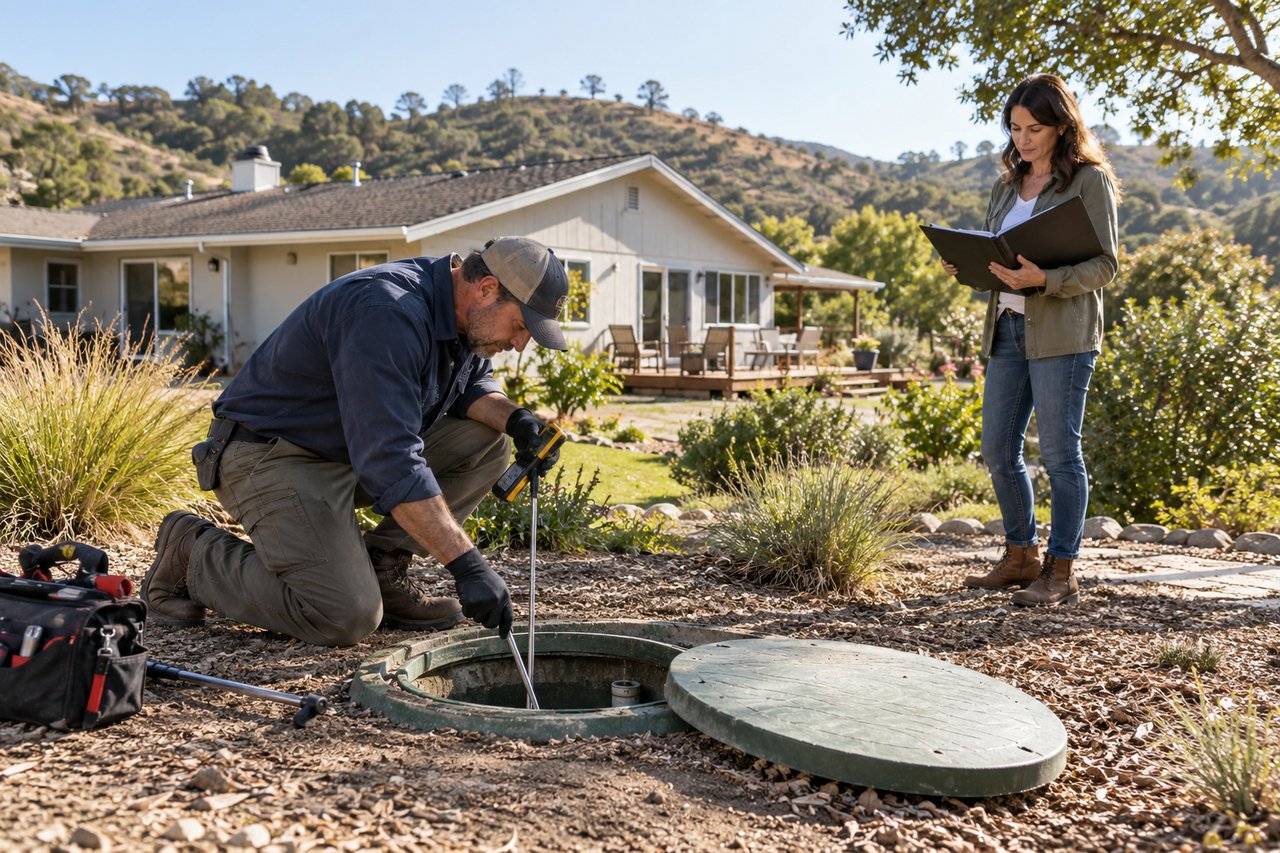
Review inspection findings, service records, capacity, access and local requirements before relying on the system.
Amber Johnson | November 8, 2026
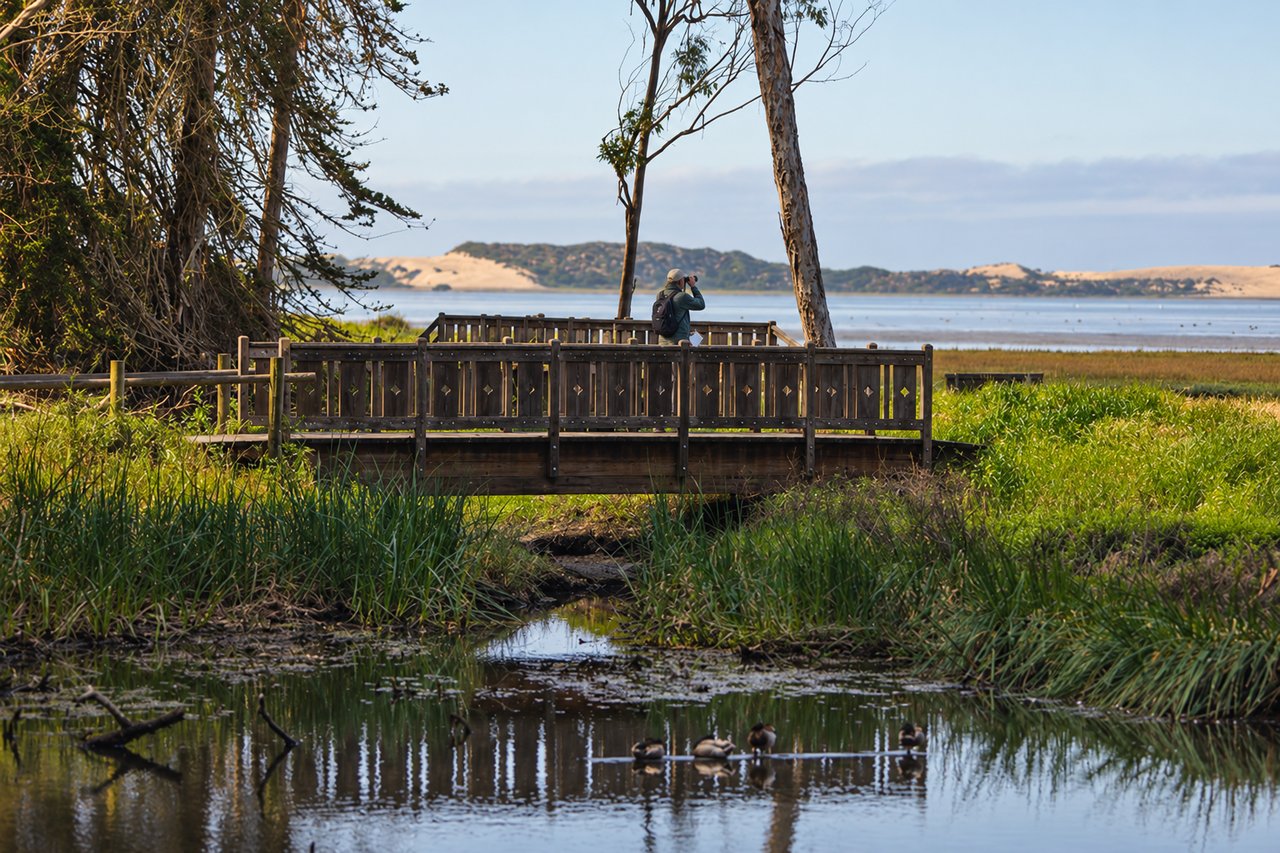
Compare access, timing, seasonal conditions and home-to-trail logistics before building regular birdwatching into life in Los Osos.
Amber Johnson | November 8, 2026
Verify the separate structure's records, condition and permitted use before counting on it.
Amber Johnson | November 7, 2026
Compare specific homes by their street setting, daily routes and access to the places you use.
Amber Johnson | November 7, 2026
Test school logistics, activities and daily routes from the specific home you are considering.
Amber Johnson | November 7, 2026
Amber Johnson | November 7, 2026
Show usable storage honestly and help buyers see how the home's layout fits daily life.
You’ve got questions and we can’t wait to answer them.
Amber Johnson, Founder
Pillar Real Estate
805.835.3425
DRE# 01925434
1345 Park Street
Paso Robles, CA 93446
